Für den Zugriff auf die beiden Plattformen können Sie jeweils dasselbe Saxo-Konto verwenden.

CoreWeave after the bond scare: what a cash-secured put pays for, and what it carries
Options 10 minutes to read
Summary: CoreWeave shares fell about a quarter in a month as its bonds traded at distressed yields. Puts now pay more than usual. What does a cash-secured put seller get paid for, and what does the seller take on?
When a company’s bonds come under pressure, its puts get more expensive. The seller collects more, and takes on more.
CoreWeave (CRWV on Nasdaq), which rents out computing power for AI, has had a hard month. Its shares closed at USD 62.13 on 20 October 2026, about a quarter lower than a month earlier and not far above their lowest level of the past year (Source: Saxo). Past performance is not indicative of future results.
Most of the damage came on 14 October, when the shares lost more than 15% in one session. The trigger was CoreWeave’s own debt: yields on its US dollar bonds climbed to levels usually seen in distressed debt, and on the bond due in 2031 investors briefly asked for more than 16% a year. The next day the selling spread to AI-related shares in Japan and South Korea (Sources: Reuters via The Star and ARY News, both 16 October 2026).
The business itself is still growing fast, and still losing money. CoreWeave reported a backlog of contracted revenue of about USD 104 billion at the end of June, and a net loss of USD 626 million for the second quarter (Source: CoreWeave Q2 2026 results, 11 August 2026). For investors already holding CoreWeave, or considering a position, options can add structure to a view they already have.
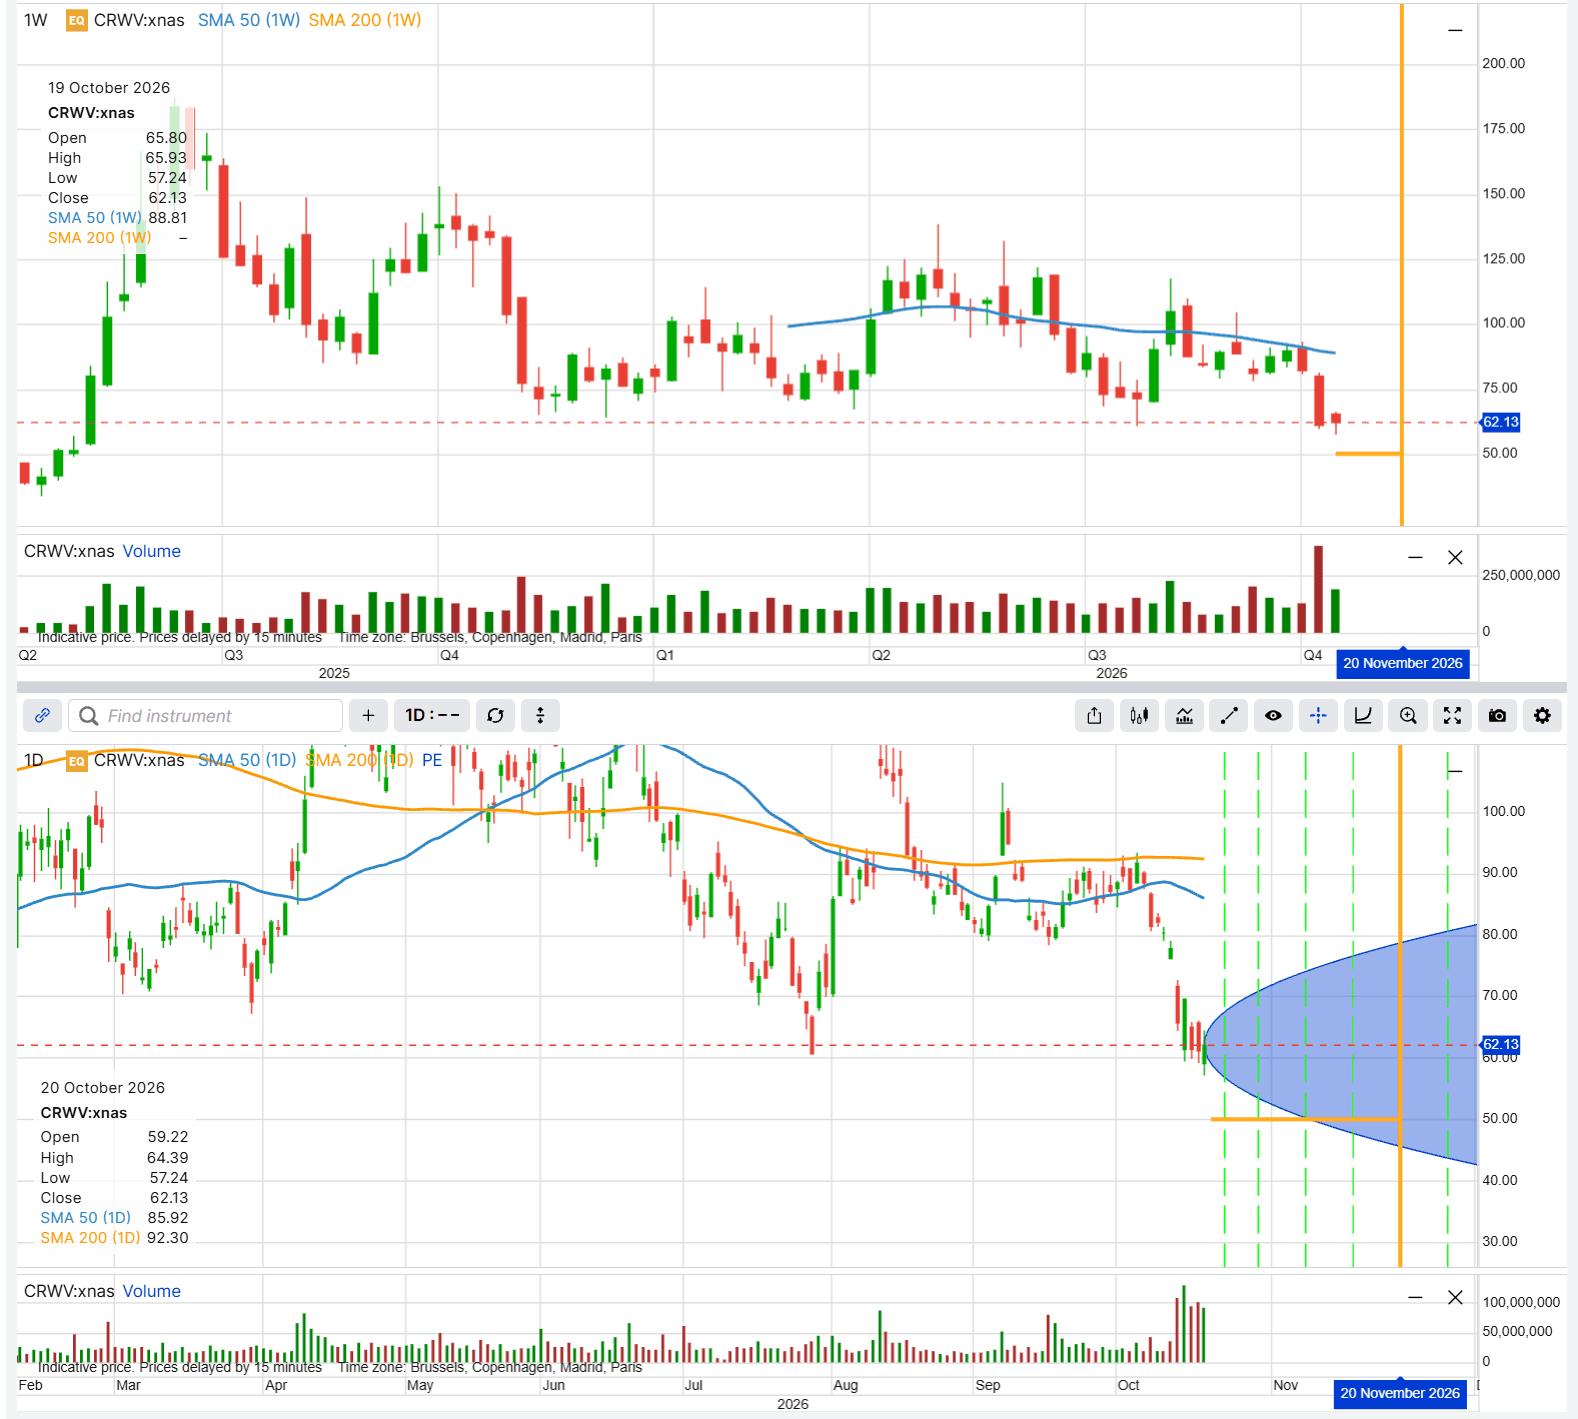 CoreWeave daily, with the 50 strike and the 20 November 2026 expiry marked. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, indicative prices, as of 20 October 2026, 22:26 CEST.
What credit stress does to put prices
When investors doubt that a company can repay its bonds, they also pay more for protection against a fall in its shares, so a put seller collects more for the same strike. A rough gauge: add the at-the-money call and put for the 20 November 2026 expiry and compare the total with the share price. For CoreWeave, that points to a move of about 23% in either direction by expiry, four to five times what options price for QQQ, the ETF that tracks the Nasdaq 100, over the same weeks. (CoreWeave: call USD 7.28 plus put USD 6.92 makes USD 14.20, on a share price of USD 62.13. Source: Saxo, indicative prices, as of 20 October 2026, 22:26 CEST.)
In our view, that gap is mostly what a CoreWeave put seller is paid for: the chance that the shares fall far and fast, as they did on 14 October. Future outcomes are uncertain and may result in losses; options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Why the 20 November 2026 expiry
The example uses the standard monthly options that expire on Friday 20 November 2026. Each contract covers 100 shares, is priced in USD and is American-style. At the strike used here, this expiry has far more open interest than the weeklies around it (Source: Saxo), and a month of time decay (theta, the small amount an option loses each day) works for the seller.
As of 20 October 2026, CoreWeave had not announced when it will report its third-quarter results. Last year it reported the third quarter on 10 November 2025 (Source: CoreWeave investor relations). On that pattern, the report would land before expiry, and a put sold now would span it, with a results-day move of its own on top of the bond story.
For the investor who wants to own CoreWeave lower: a cash-secured put at 50
Selling a cash-secured put means agreeing to buy 100 shares at the strike if CoreWeave is below it at expiry, for a premium collected today, with the cash to pay for them set aside. The view behind it: the company can work through its debt problems, and the investor would be glad to own CoreWeave at USD 50, though not at today’s price.
Hypothetical, for education only. Not advice or a trade recommendation.
Example structure (illustrative only - not a trade recommendation)
- Sell 1 CoreWeave 20 November 2026 50 put at about 2.29 (bid 2.26, ask 2.33), with the shares at USD 62.13
- Premium received: about USD 229, against USD 5,000 of cash set aside, about 4.6% of it
- Delta: about -0.19, our rough estimate, from Saxo prices, of the chance of assignment
- Purchase price if assigned: USD 47.71, about 23.2% below the price at the time
- Maximum profit: USD 229 (hypothetical); maximum loss: USD 4,771 (hypothetical), if CoreWeave fell to zero
- (Source: Saxo, indicative prices, as of 20 October 2026, 22:26 CEST)
All figures are hypothetical and for education only.
Why 50? It is about 20% below the share price, near the bottom of the range the options market prices to expiry, and plenty of contracts are already open there (Source: Saxo). A move of the size the market expects could still reach it.
Risk: the USD 229 is the whole upside, however far CoreWeave recovers. Below USD 47.71 the loss grows dollar for dollar, as it would for a shareholder. The premium does little if the debt problems get worse. In a restructuring, lenders are paid before shareholders, and the shares can fall far below any strike. Two days like 14 October in a row would take them below the break-even, and they can open sharply lower after overnight news. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the applicable rates before entering any position.
At expiry (hypothetical):
- Above USD 50: the put expires worthless and the seller keeps the USD 229.
- Between USD 47.71 and USD 50: the seller buys 100 shares at 50 and, counting the premium, is roughly flat.
- Below USD 47.71: the seller buys the shares at 50 and carries a loss that grows with every dollar lower.
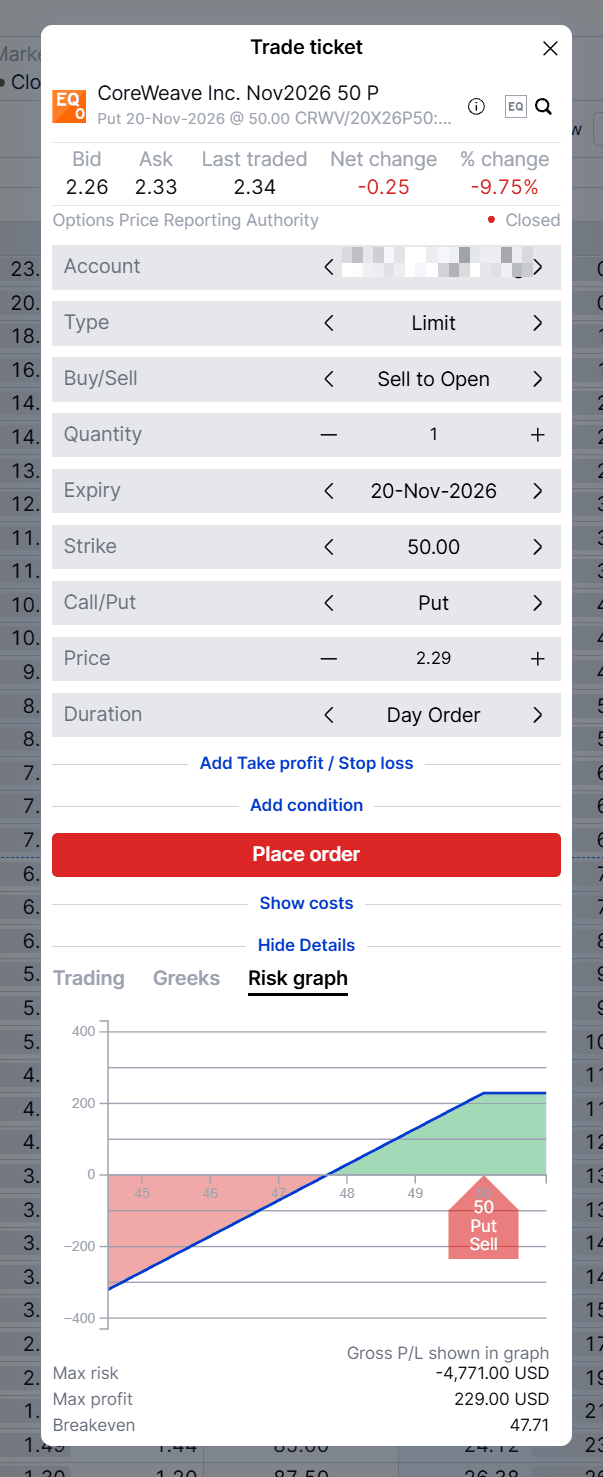
The 50 put in the SaxoTrader trade ticket, with the platform’s risk graph, maximum risk, maximum profit and break-even. Hypothetical, for education only. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, indicative prices, as of 20 October 2026, 22:26 CEST.
Testing the premise
The case against starts with the bonds. In our view, lenders who ask for around 16% a year are pricing a real chance that they will not get all their money back. An investor who reads them that way may decide the premium is too little, and stay out.
The case for points to the backlog, and to a share price that has already lost about a quarter in a month. An investor who likes the business but not the timing could wait for the third-quarter report, or use a put spread: sell the same put and buy a lower one, which caps the loss for a smaller premium.
Before placing the trade, check:
- Bid and ask spreads; selling at the bid gives up part of the premium
- That the full cash amount is set aside; the platform’s margin requirement may be lower
- An exit plan; the put can be bought back before expiry if the view changes
Assignment risk note: CoreWeave options are American-style, so a short put can be assigned before expiry if it moves in the money.
Final thoughts
In our view, this trade only suits an investor who would be comfortable owning CoreWeave at USD 50 even if the news on its debt got worse. The premium is higher than on a calmer stock because the risk is higher: if CoreWeave cannot refinance, the shares can fall well below the strike, and USD 229 does little against that. Options carry a high risk of rapid loss and are not suitable for every investor.
The author does not hold positions in any of the instruments mentioned in this article. The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
| More from the author |
|---|