us_midterms_banner_under_100kb

US midterms: Scenarios, and what they can mean for AI and bond yields
Equities 7 minutes to read

Key points:

  • Gridlock could be the most market-friendly outcome. A divided Congress may limit further fiscal expansion, potentially easing pressure on bond yields and supporting equity valuations.
  • AI faces political risks, but the bigger challenge is financing. Election outcomes could influence data-centre approvals and energy policy, but rising power costs, debt and pressure to deliver returns may matter more for AI's next phase.
  • A Republican win could favour AI infrastructure, but pressure bonds. Policy continuity may support AI, energy and financials, but concerns over deficits and higher yields could offset the benefits for equity valuations.


The US midterm elections matter for investors, but probably not because they will completely change the direction of markets.

The bigger issue is this: will the election affect the AI story and bond yields?

Right now, those are the two biggest questions for markets. AI is still a major growth story, but investors are starting to ask tougher questions about how much companies are spending, how they are funding that spending, and whether returns will justify the cost. At the same time, higher bond yields are making it harder for expensive growth stocks to keep rallying.

That is why the midterms matter. Not because one result is automatically bullish or bearish, but because each outcome could affect fiscal policy, regulation, and the ease of building AI and energy infrastructure.

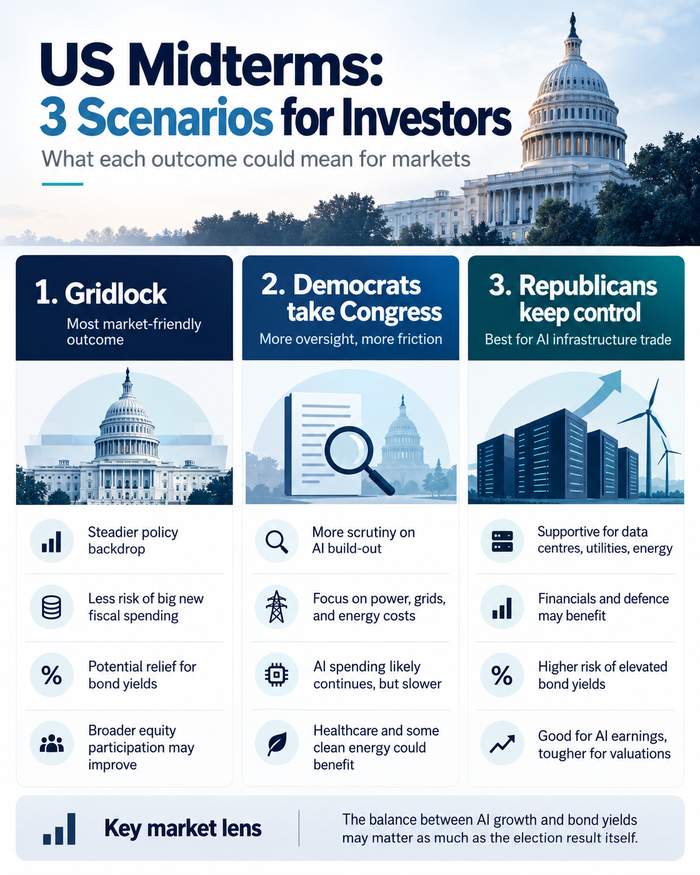
Scenario 1: Gridlock

This is probably the most market-friendly outcome.

If Democrats win one chamber and Republicans keep the other, it becomes harder to push through major policy changes. Markets often like that because it reduces the chance of large new spending plans, tax changes, or sweeping regulation.

For investors, that could be helpful if it means less fiscal pressure and a better backdrop for bonds. Lower or more stable bond yields could in turn support equity valuations, especially for growth stocks.

What it could mean for investors

  • A steadier policy backdrop
  • Less risk of another big fiscal push
  • Potential relief for bond yields
  • A better environment for broader equity participation, not just the biggest AI names
 

Scenario 2: Democrats take Congress

This would not mean a complete reversal of Trump’s agenda, because the president would still have veto power.

But it could mean more oversight, more scrutiny, and more friction around parts of the AI build-out, especially the physical side of it.

That is where the AI debate is evolving. The question is no longer just about chips and software. It is increasingly about data centres, electricity demand, grid investment, water usage, and who pays for all of it.

So the risk is not that AI stops. The risk is that the build-out becomes slower, more expensive, or more politically sensitive.

What it could mean for investors

  • More pressure on data-centre and infrastructure projects
  • Greater focus on power, utilities, grids, and energy costs
  • AI spending likely continues, but perhaps with more scrutiny
  • Healthcare and some clean-energy areas could benefit
 

Scenario 3: Republicans keep control

This is likely the most supportive outcome for the AI infrastructure trade.

It would probably mean more policy continuity, easier permitting, and stronger support for energy and infrastructure expansion. That could help areas linked to the physical build-out of AI, including data centres, utilities, nuclear, gas, copper, grid equipment, financials, and defence.

But there is an important catch.

The same outcome that supports growth and AI spending could also be more negative for bonds if markets start worrying about bigger deficits, more borrowing, and higher inflation pressure.

That means this outcome could be good for AI earnings, but less comfortable for AI valuations if bond yields keep rising.

What it could mean for investors

  • Stronger support for the AI infrastructure theme
  • Favourable backdrop for energy, financials, and defence
  • Higher risk that bond yields stay elevated
  • A more difficult backdrop for highly valued growth stocks
9CHCA_US midetrms scanarios
Source: Saxo

Bottom line

The US midterms may shape the market narrative, but they are unlikely to decide the whole market on their own.

  • Gridlock could be good for bonds, but less supportive for fiscal growth
  • Democratic control could mean lower fiscal impulse, but more regulatory friction
  • Republican control could support growth and AI infrastructure, but keep pressure on yields

For investors, the real test is whether AI investment can keep delivering growth at a time when bond yields remain high and financing conditions are tighter.

That is why the election matters. But the bigger story is still the same: AI versus yields.

Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.