Quick Take Asia

Asia Market Quick Take – 16 November, 2026

Macro 6 minutes to read

Asia Market Quick Take – 16 November, 2026 

Key points:  

  • Macro: US PPI slows. Japan Q3 GDP stalls. 
  • Equities: Reports of discussions that Jensun Huang to return as CEO 
  • FX: USD strengthens 0.7% last week, most since 2nd October 
  • Commodities: Gold near one-year lows and silver under pressure below $50 
  • Fixed income: US treasury yield curve steepened as 10 year nears 5.15% 

------------------------------------------------------------------  

qt 161126

Disclaimer: Past performance does not indicate future performance.  

 Macro:  

  • US producer prices rose 0.3% in October, down from 1.4% in September and below the 0.4% forecast. Goods inflation slowed to 0.5% on weaker energy prices, while food rose 1.3% and services 0.2%. Core PPI (excluding food and energy) rose 0.3%, and the measure excluding food, energy, and trade services rose 0.5%. Year-over-year, headline PPI hit 6.5% and core 5.0%.
  • Iran launched six drones at a US air base in Bahrain, all intercepted, and said an oil tanker hit a naval mine near the Strait of Hormuz. Trump stated the US does not need an Iran deal, adding to geopolitical tensions and supporting higher oil prices.
  • Japan’s economy contracted an annualized 0.1% in Q3 2026, missing expectations for 0.1% growth and reversing a 1.7% expansion in Q2, as weaker consumption, lower government spending, and net trade drag outweighed a rebound in business investment.
  • Nvidia co-founder Jensen Huang is reportedly considering returning as CEO, with Silicon Valley allies pushing the board to reinstate him, FT reports. US Treasury Secretary Bessent, meanwhile, said Nvidia needs an external CEO “shake-up” and called for a review of its compliance with US export controls.

Equities:  

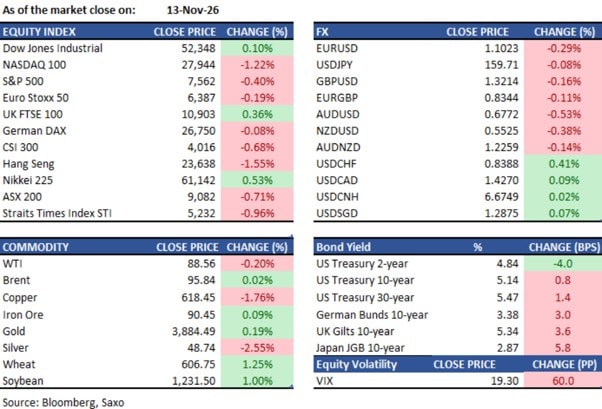
  • US — The S&P 500 closed Friday down 0.4% at 7,561.67, while the Nasdaq 100 shed 1.2% as chipmakers led declines. The Dow added 50 points. Despite Friday's weakness, both the S&P 500 and Nasdaq 100 posted weekly gains — the S&P 500's first in five weeks — as a post-midterm rally and AI infrastructure demand offset Nvidia's implosion. Nvidia fell 13% last week, its worst since April 2025, wiping over $500 billion in market value. AMD and Broadcom also declined Friday. In after-hours, Nvidia futures indicated up approximately 4.5% on reports of Huang's potential comeback. Airlines were under pressure in post-market trading while cybersecurity stocks caught a bid after US authorities halted flights.
  • EU — The Stoxx Europe 600 gained 2.4% last week — its best week since July — closing at a record high, outperforming US peers amid the AI trade unwind. The FTSE 100 hit its highest close since July 29 at 10,902.56. Shell led gains in both the Stoxx 600 and FTSE 100, rising 1.5% on Friday. Infineon dropped 4.3% in Frankfurt. However, State Street, Pictet, and BofA have all turned cautious on European equities, with BofA cutting to underweight and warning of up to 15% downside by Q2 2027.
  • Asia — Asian markets are opening cautiously this Monday. The ASX 200 fell 0.2% in early trade, dragged by mining and banking stocks, though futures edged higher on the Huang comeback report. Nikkei and Kospi futures are modestly firmer but sentiment is nervous ahead of Anthropic's IPO details and Nvidia earnings. The Kospi has formed a technical "death cross" with the 50-day moving average falling below the 200-day line. In Japan, Mizuho surged as much as 6.5% — its biggest move in seven months — after raising net income guidance and its dividend. Appier rose 12% and Asahi Intecc gained 8% on strong earnings, while Nabtesco fell 10% after missing operating income estimates. Goldman Sachs upgraded Hong Kong-listed Chinese stocks to overweight for 2027. Taiwan saw record foreign outflows in October but global fund buying hit a one-month high on November 13.

Earnings this week: 

  • Monday – XPeng ADR, Baidu ADR 
    Tuesday – Home Depot, Walt Disney, JD.com, Nvidia 
    Wednesday – Target, Lowe’s, Tencent ADR, Palo Alto 
    Thursday – PDD ADR, Walmart, Alibaba ADR, Futu, Intuit 
    Friday – No key earnings

FX: 

  • USD broadly firm with the Bloomberg Dollar Spot Index rose 0.7% last week — its largest weekly gain since October 2 — touching its highest level since May 2025, driven by rising Fed rate hike expectations following hot CPI data. The dollar is quoted slightly softer in early Monday Asian trading.
  • USDJPY is trading at approximately 159.82, nearing the closely watched 160 level. Japanese Finance Minister Katayama warned of "one-sided, rapid moves" and pledged to work with the US Treasury on appropriate action. Caution over yen-buying intervention remains elevated.
  • AUDUSD is consolidating near 0.6777, its lowest level since January 23, after falling 1.4% last week. Commonwealth Bank of Australia expects AUDUSD to remain weak around 0.68. RBA minutes and jobs data are due this week.
  • NZDUSD is at approximately 0.5527, with bearish momentum keeping risks skewed to the downside. The next key support is the 2025 low near 0.5486.

Commodities: 

  • Gold is trading near $3,880 per ounce, having briefly hit a 13-month low last week after falling nearly 3% in a single session. Persistent inflation and rising Fed rate hike bets are the primary headwinds, with Trump's comments ruling out an Iran deal adding to upward pressure on yields and the dollar.
  • Crude prices remain supported after Iran launched drones at Bahrain and an oil tanker reportedly hit a mine east of the Strait of Hormuz over the weekend. Trump's statement that the US does not need an Iran deal has reinforced supply risk premiums. Brent had previously surged above $100 per barrel on these tensions.

Fixed income:  

  • The US 10-year yield closed Friday at approximately 5.14%–5.15%, with two-year yields surging as much as 37 basis points last week following the hot CPI print and hawkish Fedspeak. The 2s10s curve steepened on Friday as front-end yields dipped slightly while the long end rose. Bond traders are now looking to this week's Fed meeting minutes and a slate of Fed speakers for further direction.
  • Markets are pricing close to 30bp for the next Fed meeting, effectively fully pricing a December hike. RBC Capital Markets sees a high probability of back-to-back hikes in December and January. Man Group's Matthew Rowe sees the 10-year yield potentially reaching 5.5% early next year as stagflation risks build.
  • UK and German government bond yields are also rising, with the BOE under pressure to hike again as UK CPI is expected to hit a one-year high of 3.6% on Wednesday. Multiple central bank officials from the US, UK, and eurozone signalled further rate increases are needed at a London gathering last week, reinforcing the global tightening narrative.

For a global look at markets – go to Inspiration.  

This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information. 

Quarterly Outlook

01 /

  • Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    Quarterly Outlook

    Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    John J. Hardy

    Global Head of Macro Strategy

    Strap yourself in for key market questions that must be answered in 2026.
  • Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Quarterly Outlook

    Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Charu Chanana

    Chief Investment Strategist

    2026 is a high-valuation, high-dispersion year: the AI story matures, policy becomes less predictabl...
  • Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Quarterly Outlook

    Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    Quarterly Outlook

    Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    John J. Hardy

    Global Head of Macro Strategy

    The Fed launched a new easing cycle in late Q3. Will this cycle now play out like 2000 or 2007?
  • Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Quarterly Outlook

    Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    Quarterly Outlook

    Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    John J. Hardy

    Global Head of Macro Strategy

    After the chaos of Q2, the quarter ahead should get a bit more clarity on how Trump 2.0 is impacting...
  • Equity outlook: The high cost of global fragmentation for US portfolios

    Quarterly Outlook

    Equity outlook: The high cost of global fragmentation for US portfolios

    Charu Chanana

    Chief Investment Strategist

  • Commodity Outlook: Commodities rally despite global uncertainty

    Quarterly Outlook

    Commodity Outlook: Commodities rally despite global uncertainty

    Ole Hansen

    Head of Commodity Strategy

  • Upending the global order at blinding speed

    Quarterly Outlook

    Upending the global order at blinding speed

    John J. Hardy

    Global Head of Macro Strategy

    We are witnessing a once-in-a-lifetime shredding of the global order. As the new order takes shape, ...
  • Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Quarterly Outlook

    Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Jacob Falkencrone

    Global Head of Investment Strategy

Disclaimer

The Saxo Group entities each provide execution-only service and access to Analysis permitting a person to view and/or use content available on or via the website is not intended to and does not change or expand on this. Such access and use are at all times subject to (i) The Terms of Use; (ii) Full Disclaimer; (iii) The Risk Warning; (iv) the Rules of Engagement and (v) Notices applying to Saxo News & Research and/or its content in addition (where relevant) to the terms governing the use of hyperlinks on the website of a member of the Saxo Group by which access to Saxo News & Research is gained. Such content is therefore provided as no more than information. In particular no advice is intended to be provided or to be relied on as provided nor endorsed by any Saxo Group entity; nor is it to be construed as solicitation or an incentive provided to subscribe for or sell or purchase any financial instrument. All trading or investments you make must be pursuant to your own unprompted and informed self-directed decision. As such no Saxo Group entity will have or be liable for any losses that you may sustain as a result of any investment decision made in reliance on information which is available on Saxo News & Research or as a result of the use of the Saxo News & Research. Orders given and trades effected are deemed intended to be given or effected for the account of the customer with the Saxo Group entity operating in the jurisdiction in which the customer resides and/or with whom the customer opened and maintains his/her trading account. Saxo News & Research does not contain (and should not be construed as containing) financial, investment, tax or trading advice or advice of any sort offered, recommended or endorsed by Saxo Group and should not be construed as a record of our trading prices, or as an offer, incentive or solicitation for the subscription, sale or purchase in any financial instrument. To the extent that any content is construed as investment research, you must note and accept that the content was not intended to and has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such, would be considered as a marketing communication under relevant laws.

Please read our disclaimers:
- Notification on Non-Independent Investment Research (https://www.home.saxo/legal/niird/notification)
- Full disclaimer (https://www.home.saxo/en-hk/legal/disclaimer/saxo-disclaimer)

None of the information contained here constitutes an offer to purchase or sell a financial instrument, or to make any investments. Saxo does not take into account your personal investment objectives or financial situation and makes no representation and assumes no liability as to the accuracy or completeness of the information nor for any loss arising from any investment made in reliance of this presentation. Any opinions made are subject to change and may be personal to the author. These may not necessarily reflect the opinion of Saxo or its affiliates.


Hong Kong

Contact Saxo

Hong Kong S.A.R
Hong Kong S.A.R

Saxo Capital Markets HK Limited (“Saxo”) is a company authorised and regulated by the Securities and Futures Commission of Hong Kong. Saxo holds a Type 1 Regulated Activity (Dealing in Securities); Type 2 Regulated Activity (Dealing in Futures Contract); Type 3 Regulated Activity (Leveraged Foreign Exchange Trading); Type 4 Regulated Activity (Advising on Securities) and Type 9 Regulated Activity (Asset Management) licenses (CE No. AVD061). Registered address: 19th Floor, Shanghai Commercial Bank Tower, 12 Queen’s Road Central, Hong Kong.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products may result in your losses exceeding your initial deposits. Saxo does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo does not take into account an individual’s needs, objectives or financial situation. Please click here to view the relevant risk disclosure statements.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-hk/about-us/awards.

The information or the products and services referred to on this site may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and services offered on this website are not directed at, or intended for distribution to or use by, any person or entity residing in the United States and Japan. Please click here to view our full disclaimer.

Apple, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. AppStore is a service mark of Apple Inc. Android is a trademark of Google Inc.