Quick Take Asia

Asia Market Quick Take – 21 October, 2026

Macro 6 minutes to read

Asia Market Quick Take – 21 October, 2026 

Key points:  

  • Macro: US ADP rose; UK unemployment falls to 4.7% 
  • Equities: Dow outperforms rising 1% 
  • FX: Pound was among the top G10 performers and yuan strengthens 
  • Commodities: Oil whipsawed & gold under pressure. 
  • Fixed income: Treasuries bull-flattened with real yields declining 

------------------------------------------------------------------  

qt 211026
 

Disclaimer: Past performance does not indicate future performance.  

 Macro:  

  • ADP Weekly Payrolls showed US private payrolls rose an average of 18,500 per week in the four weeks to 3 October, highlighting a modestly softening labour market.
  • Japan’s exports rose 16.7% yoy in September 2026, below the 20.1% consensus and the softest growth in 13 months, despite strong AI‑related chip and semiconductor demand and broad-based gains across major destinations and categories.
  • US pending home sales fell 7.3% m/m in September 2026 to a record low, far worse than the expected 0.5% drop, as surging mortgage rates hit affordability and dragged down activity across all regions.
  • Pakistan’s army chief Asim Munir met senior Iranian officials in Tehran to discuss bilateral ties and talks with Washington, but a participating diplomat denied an imminent deal while confirming negotiations continue.
  • The UK unemployment rate fell to 4.7% in the three months to August 2026, beating expectations for 4.9% and reaching its lowest since mid‑2025, as unemployment declined and employment rose, pushing the employment rate up to 75.3% and nudging inactivity lower.
  • Governor Kazuo Ueda said underlying inflation is nearing the BOJ’s 2% target amid a moderate recovery and tight labor market, driven by higher Middle Eastern energy costs and strong AI‑related demand.

Equities:  

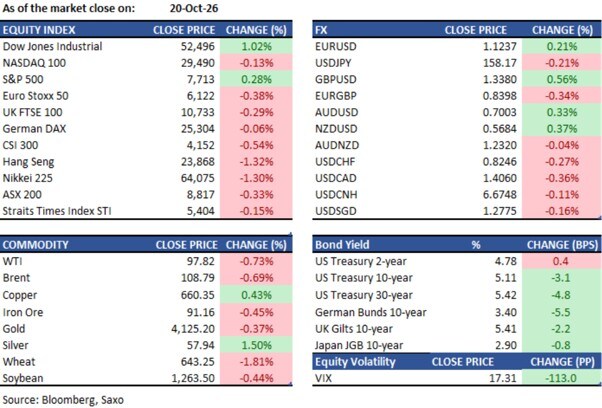
  • US: US equities closed mixed as strong earnings offset AI credit concerns. The Dow Jones Industrial Average jumped 1.0% to 52,495.88, the S&P 500 rose 0.3% to 7,712.57 led by healthcare stocks, while the Nasdaq Composite edged down 0.02% to 26,424.82. Key movers: Equifax surged 11.3%, Eli Lilly gained 3.5%, and GM fell 7.6% after CEO Mary Barra warned of "intensifying" challenges and narrowed guidance. In after-hours trading, SpaceX posted $4.4 billion in net income, well above the $1.88 billion consensus, lifting S&P 500 ETFs. Tesla also gained 2% after Musk said he likes the idea of Tesla and SpaceX merging. Capital One rose 4.5% post-market on a strong earnings beat. Netflix sank on a disappointing subscriber update. Super Micro Computer jumped 15% after preliminary sales results $18.5-$19.5b vs estimate of $15b.
  • EU: European equities drifted lower, weighed by AI jitters and French political risk. The Stoxx 600 fell 0.1% to 638.64, with ASML down 2.7% the largest drag. The FTSE 100 dropped 0.3% to 10,733, with HSBC the biggest contributor to losses and Diploma falling 4.0%. The DAX was little changed at 25,304, with Brenntag the worst performer at -3.4%. The SMI outperformed, rising 0.8% to 14,478 led by Roche (+2.6%). The OMX Stockholm fell 0.9%, dragged by ABB (-4.9%). French stocks continued to underperform amid ongoing cost-of-living protests and fiscal concerns, with French 10-year OAT yields holding near multi-year highs at 4.95%.
  • Asia: Asian equities fell sharply on Tuesday as AI trade jitters and rate fears dominated. The MSCI Asia Pacific Index dropped as much as 1.2%. The Hang Seng Index fell 1.3% to 23,867.74, with Alibaba down 3.6% and Lenovo tumbling 10.0% after Citi cut its price target by 20%. CATL fell sharply ahead of earnings that subsequently missed estimates — net income rose 15% year-on-year to 21.25 billion yuan, well below the 26 billion yuan consensus. The Kospi plunged 3.7% to 5,552.74, with Samsung Electronics and SK Hynix each falling around 3–4% on AI spending concerns and the Elice IPO debacle. The STI slipped 0.1% to 5,404.02, with Yangzijiang Shipbuilding the worst performer at -3.1%. The Nikkei 225 also declined. However, sentiment has sharply reversed overnight: as of early Wednesday, the MSCI Asia Pacific Index is up 0.6%, the Kospi has rebounded 1.9%, and Nasdaq 100 futures are up 0.7% on the back of SpaceX and Super Micro earnings beats.

Earnings this week: 

  • Wednesday: Abbott, NextEra Energy, AT&T, CME Group, Danaher, Tesla, Meta, IBM, Lam Research, Texas Instruments, Philip Morris 
  • Thursday: Lockheed Martin, Nokia, Comcast, American Airlines, Bloom Energy 
  • Friday: American Express, Schlumberger 

FX: 

  • All G10 currencies advanced against the greenback at the session's weakest point for the dollar.
  • USDJPY has slipped past 158, trading at 158.34 this morning (+0.1% on the day). The pair has traded in a tight 200-pip range over the past 20 days, with analysts noting the range increasingly resembles a managed currency. A Fed rate hike remains the clearest catalyst for a topside break.
  • GBPUSD is at 1.3374, holding above its 21-day moving average for the first time since late August, reinforcing near-term topside dynamics. The pound was among the top G10 performers during Tuesday's dollar weakness.
  •  The yuan strengthened modestly onshore and offshore on Tuesday as the dollar weakened alongside falling oil prices.

Commodities: 

  • Brent crude hit a five-month intraday high above $111 a barrel on Tuesday before reversing sharply, settling at $108.79 (-0.69%) after a diplomat confirmed that reports of an imminent US-Iran peace deal were inaccurate. WTI settled near $98 a barrel. The session saw a range of over $6 for Brent. Iranian IRGC reported tankers struck mines in the Strait of Hormuz, and Iran added 122 tankers to its sanctions list. Brent is currently at $109.50 and WTI at $98.50.
  • Gold settled at $4,122.40 on Tuesday (-0.40%), its second consecutive session of losses, as elevated oil prices fuelled inflation concerns and clouded the Fed rate path. Bullion is trading around $4,117 this morning, down more than 1% since the start of the week and approximately 22% below its January 2026 peak of $5,318. ETF gold holdings continue to rise, reaching a four-year high, but leveraged players have reduced exposure.

Fixed income:  

  • The curve aggressively twist-flattened, with the long end rallying on haven demand from AI jitters and lower oil prices. The 10-year yield fell 2.6 basis points to 5.117%, while the 30-year fell 4.7 basis points to 5.424%. The front end was little changed, with the 1-year yield at 4.482%. The 5s30s spread compressed to 49.1 basis points from 52.9 basis points.
  • US 10-year real yields fell 4.9 basis points to 2.74% on Tuesday, though they remain 81 basis points higher year-to-date. September CPI was 3.7% year-on-year, keeping the inflation backdrop elevated. Treasury options markets showed two consecutive days of demand for downside protection targeting a 10-year yield rise to 5.3% by month-end, suggesting the market is not fully convinced the rally has legs.
  • French 10-year yields held near multi-year highs at 4.95%, extending underperformance versus Bunds. French bonds remain under pressure from ongoing cost-of-living protests and fiscal concerns, with a record share of investors reportedly underweighting French equities. US high-yield credit also remains stressed, with CCC spreads at 1,072 basis points — the widest since October 2022.

For a global look at markets – go to Inspiration.  

This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.  


Quarterly Outlook

01 /

  • Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    Quarterly Outlook

    Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    John J. Hardy

    Global Head of Macro Strategy

    Strap yourself in for key market questions that must be answered in 2026.
  • Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Quarterly Outlook

    Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Charu Chanana

    Chief Investment Strategist

    2026 is a high-valuation, high-dispersion year: the AI story matures, policy becomes less predictabl...
  • Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Quarterly Outlook

    Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    Quarterly Outlook

    Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    John J. Hardy

    Global Head of Macro Strategy

    The Fed launched a new easing cycle in late Q3. Will this cycle now play out like 2000 or 2007?
  • Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Quarterly Outlook

    Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    Quarterly Outlook

    Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    John J. Hardy

    Global Head of Macro Strategy

    After the chaos of Q2, the quarter ahead should get a bit more clarity on how Trump 2.0 is impacting...
  • Equity outlook: The high cost of global fragmentation for US portfolios

    Quarterly Outlook

    Equity outlook: The high cost of global fragmentation for US portfolios

    Charu Chanana

    Chief Investment Strategist

  • Commodity Outlook: Commodities rally despite global uncertainty

    Quarterly Outlook

    Commodity Outlook: Commodities rally despite global uncertainty

    Ole Hansen

    Head of Commodity Strategy

  • Upending the global order at blinding speed

    Quarterly Outlook

    Upending the global order at blinding speed

    John J. Hardy

    Global Head of Macro Strategy

    We are witnessing a once-in-a-lifetime shredding of the global order. As the new order takes shape, ...
  • Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Quarterly Outlook

    Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Jacob Falkencrone

    Global Head of Investment Strategy

Disclaimer

The Saxo Group entities each provide execution-only service and access to Analysis permitting a person to view and/or use content available on or via the website is not intended to and does not change or expand on this. Such access and use are at all times subject to (i) The Terms of Use; (ii) Full Disclaimer; (iii) The Risk Warning; (iv) the Rules of Engagement and (v) Notices applying to Saxo News & Research and/or its content in addition (where relevant) to the terms governing the use of hyperlinks on the website of a member of the Saxo Group by which access to Saxo News & Research is gained. Such content is therefore provided as no more than information. In particular no advice is intended to be provided or to be relied on as provided nor endorsed by any Saxo Group entity; nor is it to be construed as solicitation or an incentive provided to subscribe for or sell or purchase any financial instrument. All trading or investments you make must be pursuant to your own unprompted and informed self-directed decision. As such no Saxo Group entity will have or be liable for any losses that you may sustain as a result of any investment decision made in reliance on information which is available on Saxo News & Research or as a result of the use of the Saxo News & Research. Orders given and trades effected are deemed intended to be given or effected for the account of the customer with the Saxo Group entity operating in the jurisdiction in which the customer resides and/or with whom the customer opened and maintains his/her trading account. Saxo News & Research does not contain (and should not be construed as containing) financial, investment, tax or trading advice or advice of any sort offered, recommended or endorsed by Saxo Group and should not be construed as a record of our trading prices, or as an offer, incentive or solicitation for the subscription, sale or purchase in any financial instrument. To the extent that any content is construed as investment research, you must note and accept that the content was not intended to and has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such, would be considered as a marketing communication under relevant laws.

Please read our disclaimers:
- Notification on Non-Independent Investment Research (https://www.home.saxo/legal/niird/notification)
- Full disclaimer (https://www.home.saxo/en-hk/legal/disclaimer/saxo-disclaimer)

None of the information contained here constitutes an offer to purchase or sell a financial instrument, or to make any investments. Saxo does not take into account your personal investment objectives or financial situation and makes no representation and assumes no liability as to the accuracy or completeness of the information nor for any loss arising from any investment made in reliance of this presentation. Any opinions made are subject to change and may be personal to the author. These may not necessarily reflect the opinion of Saxo or its affiliates.


Hong Kong

Contact Saxo

Hong Kong S.A.R
Hong Kong S.A.R

Saxo Capital Markets HK Limited (“Saxo”) is a company authorised and regulated by the Securities and Futures Commission of Hong Kong. Saxo holds a Type 1 Regulated Activity (Dealing in Securities); Type 2 Regulated Activity (Dealing in Futures Contract); Type 3 Regulated Activity (Leveraged Foreign Exchange Trading); Type 4 Regulated Activity (Advising on Securities) and Type 9 Regulated Activity (Asset Management) licenses (CE No. AVD061). Registered address: 19th Floor, Shanghai Commercial Bank Tower, 12 Queen’s Road Central, Hong Kong.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products may result in your losses exceeding your initial deposits. Saxo does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo does not take into account an individual’s needs, objectives or financial situation. Please click here to view the relevant risk disclosure statements.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-hk/about-us/awards.

The information or the products and services referred to on this site may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and services offered on this website are not directed at, or intended for distribution to or use by, any person or entity residing in the United States and Japan. Please click here to view our full disclaimer.

Apple, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. AppStore is a service mark of Apple Inc. Android is a trademark of Google Inc.