Un seul compte Saxo suffit pour accéder à nos plateformes.

Premium leaves today and fills the week - Options Brief - 29 September 2026
Options 10 minutes to read
Résumé: Monday marked almost every volatility measure on the board higher and exactly one lower, and the one it marked lower was today. What does the nine-day window know about the rest of this week?
Monday marked almost every volatility measure on the board higher. It marked one lower, and that one was today.
MARKET REGIME: LOW VOL BULL | VIX 16.07 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (146.25) | FRONT-MONTH VIX FUTURES: 17.85
Key findings
- The front split. VIX1D fell 9.91% to 11.27 while VIX9D rose 12.77% to 14.39, the largest moves on the board in each direction.
- Rates carry the bid. MOVE rose 6.06% to 101.82, higher than 59 of the previous 60 readings, with the ten-year above 5.25%.
- Metals moved, metals options did not. The gold fund fell 3.94% and GVZ rose 10.65%, yet the metals group's median implied-volatility rank is just 24.1.
The news moved oil for a morning. What stuck was the rate path. President Trump rejected Iran's proposal to reopen the Strait of Hormuz, and crude spiked on the headline: the front WTI contract traded as high as 96.54 before settling at 92.60, a gain of 0.21% on the session. Almost the whole move was handed back inside the day.
The inflation read was not handed back. Treasury yields set fresh cycle highs along the curve, the thirty-year printing 5.58%, its highest since 2004, and the ten-year trading above 5.25% by early Tuesday. Saxo puts the ten-year real yield near 2.9%, an eighteen-year high.
That combination is what broke the metals. The gold fund fell 3.94% to 377.91 and the silver fund 5.49% to 54.95, with gold touching a seven-week low. Equities gave up September: the S&P 500 fell 0.77% to 7,683.69.
- US (Monday 28 September close): The S&P 500 fell 0.77% to 7,683.69, the Nasdaq 100 1.08% to 30,276.81 and the Dow 347 points to 51,487.16. Only two of the eleven sector funds tracked here rose, health care at 0.33% and energy at 0.10%; communication services was weakest at 1.58% lower. Nvidia gained 1.68% on a record buyback, against Meta Platforms 4.79% and Tesla 3.94% lower.
- Europe: The Stoxx Europe 600 closed unchanged at 638.68 and the DAX fell 0.13%, shrugging off the move in yields. UK housebuilders surged on a first-time buyer loan programme; Fresnillo was the weakest London blue chip at 5.1% lower alongside silver.
- Asia (Tuesday morning): Tracking Monday's US decline: the Nikkei 225 is 1.27% lower, the Kospi 1.05% and the Hang Seng 0.63%, with the CSI 300 flat.
- Commodities and rates: The gold fund fell 3.94% to 377.91, silver 5.49% and the gold miners fund 5.36%. Oil is split across contracts, Brent above 107 on the expiring November and December just under 100, so no session change is drawn. The ten-year yield is 5.255% early on Tuesday, about five basis points above the same hour Monday, the thirty-year 5.569%. High-yield credit spreads widened nine basis points to 303, the widest since April.
- Market regime: Low Vol Bull, with the VIX at 16.07, the cash curve in contango and twenty-day realised volatility at 10.83%.
Source: Saxo, Bloomberg, CBOE. Levels as of the 28 September close unless stated. Past performance is not indicative of future results.
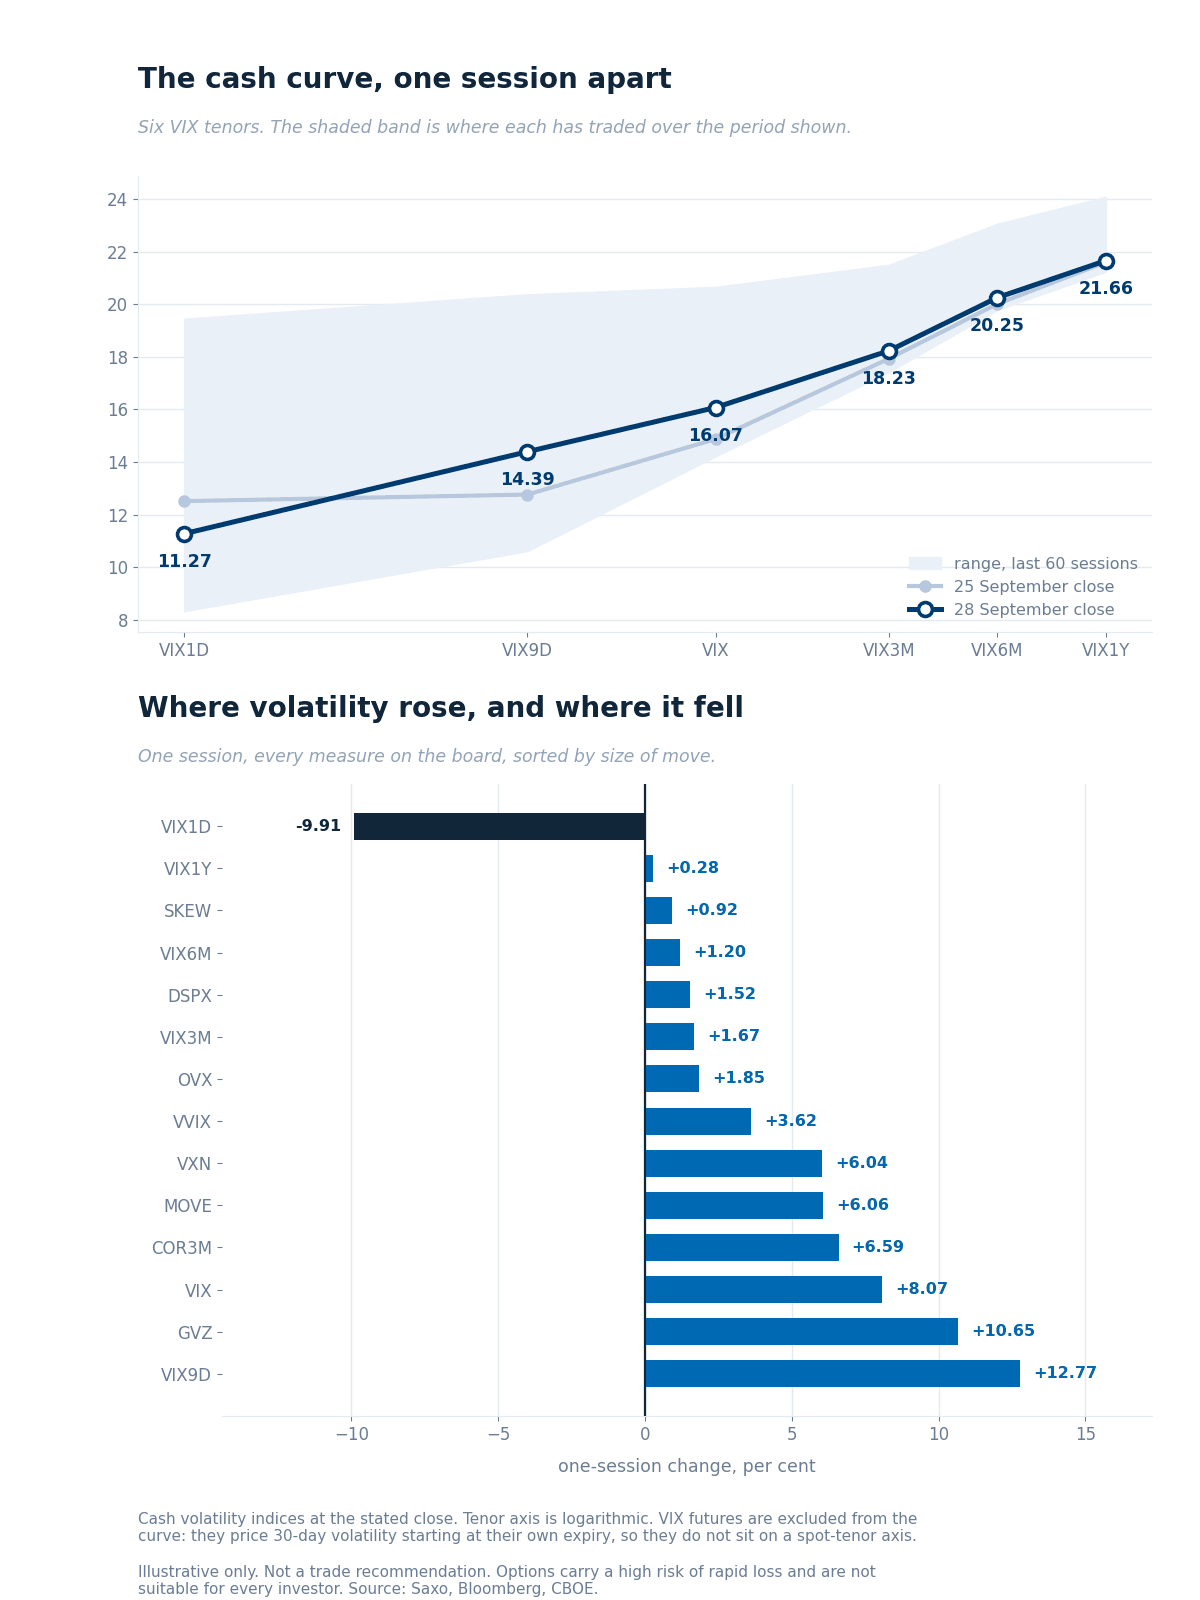 The six cash VIX tenors at Monday's close against the previous session and the 60-session range of each, with every measure's one-session change below.
Reading the curve
- One measure fell. VIX1D lost 9.91% to 11.27; everything else rose, led by VIX9D at 12.77% and GVZ at 10.65%. The VIX added 8.07%, VIX3M 1.67% and VIX1Y 0.28%, concentrating the lift where this week's data sits.
- Behind the front the curve is still cheap. VIX3M sits at 20% of its 60-session range, VIX6M at 14% and VIX1Y at 15%. MOVE is the exception on the whole board at 92%, with only one of the previous 60 readings higher.
- Ratios, which the graphic does not carry. VIX3M to VIX fell to 1.13 from 1.21, with 47 of the previous 60 steeper, so the curve flattened from the front up rather than the back down.
VIX futures
- The feed shows the front contract at 17.850 and the second at 18.510. The chain returned no two-sided quotes this morning, so the put-call parity check that verifies those levels could not be run, and no change or premium to spot is drawn.
- Neither sits in the graphic: both price 30-day volatility starting at their own expiry.
Data source: Saxo, Bloomberg, CBOE, as of 29 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Saxo's implied-volatility rank across 187 US and 335 euro-zone option underlyings, where 0 is a one-year low and 100 a one-year high. Both universes held the same membership across the two sessions, so the comparison is like for like.
- The typical name got dearer, and almost all of them did. The median US rank rose to 42.3 from 36.7 and the median percentile to 55.2 from 45.2. 151 of the 187 US names rose in rank, and 302 of the 335 euro-zone names.
- Rates and credit sit at the top. The long-bond fund prices 15.21% implied volatility on a rank of 87.6 and a percentile of 98.8, up from a rank of 72.9 in one session. Against its own year it is dearer than roughly ninety-nine sessions in a hundred.
- Metals is the exception, and the interesting one. The group's median rank is 24.1, second lowest of the ten tracked, on the session gold and silver broke hardest. The silver fund is the cheapest name in it at a rank of 8.9; the gold fund rose only to 22.2 from 13.2. A violent price move and a dear option are not the same thing.
- Micron prices 61.21% implied volatility on a rank of 26.4, the day before it reports. See Saxo pricing for costs and charges.
Data source: Saxo, as of 29 September 2026, reflecting the 28 September close. Day counts are Saxo's one-year implied-volatility percentile. Past performance is not indicative of future results.
Based on end-of-day 28 September, Monday's positioning and not today's price action.
- Single-name flow gave no readable direction. The largest packages in every group crossed at mid as multi-leg structures with no initiator evidence, and in several groups one unsided package was a quarter or more of the day's confirmed-opening premium.
- Sector and ETF flow was shaped the same way. The one strand that reads cleanly is that size was opened weeks to years out while the front week saw premium supplied, which is consistent with the term-structure move above but is context rather than evidence. Metals positioning does not corroborate a metals-led volatility bid. Named funds are market context only; see Saxo pricing for costs and charges on exchange-traded fund trades.
What the option market priced for this week, drawn around Friday's close.
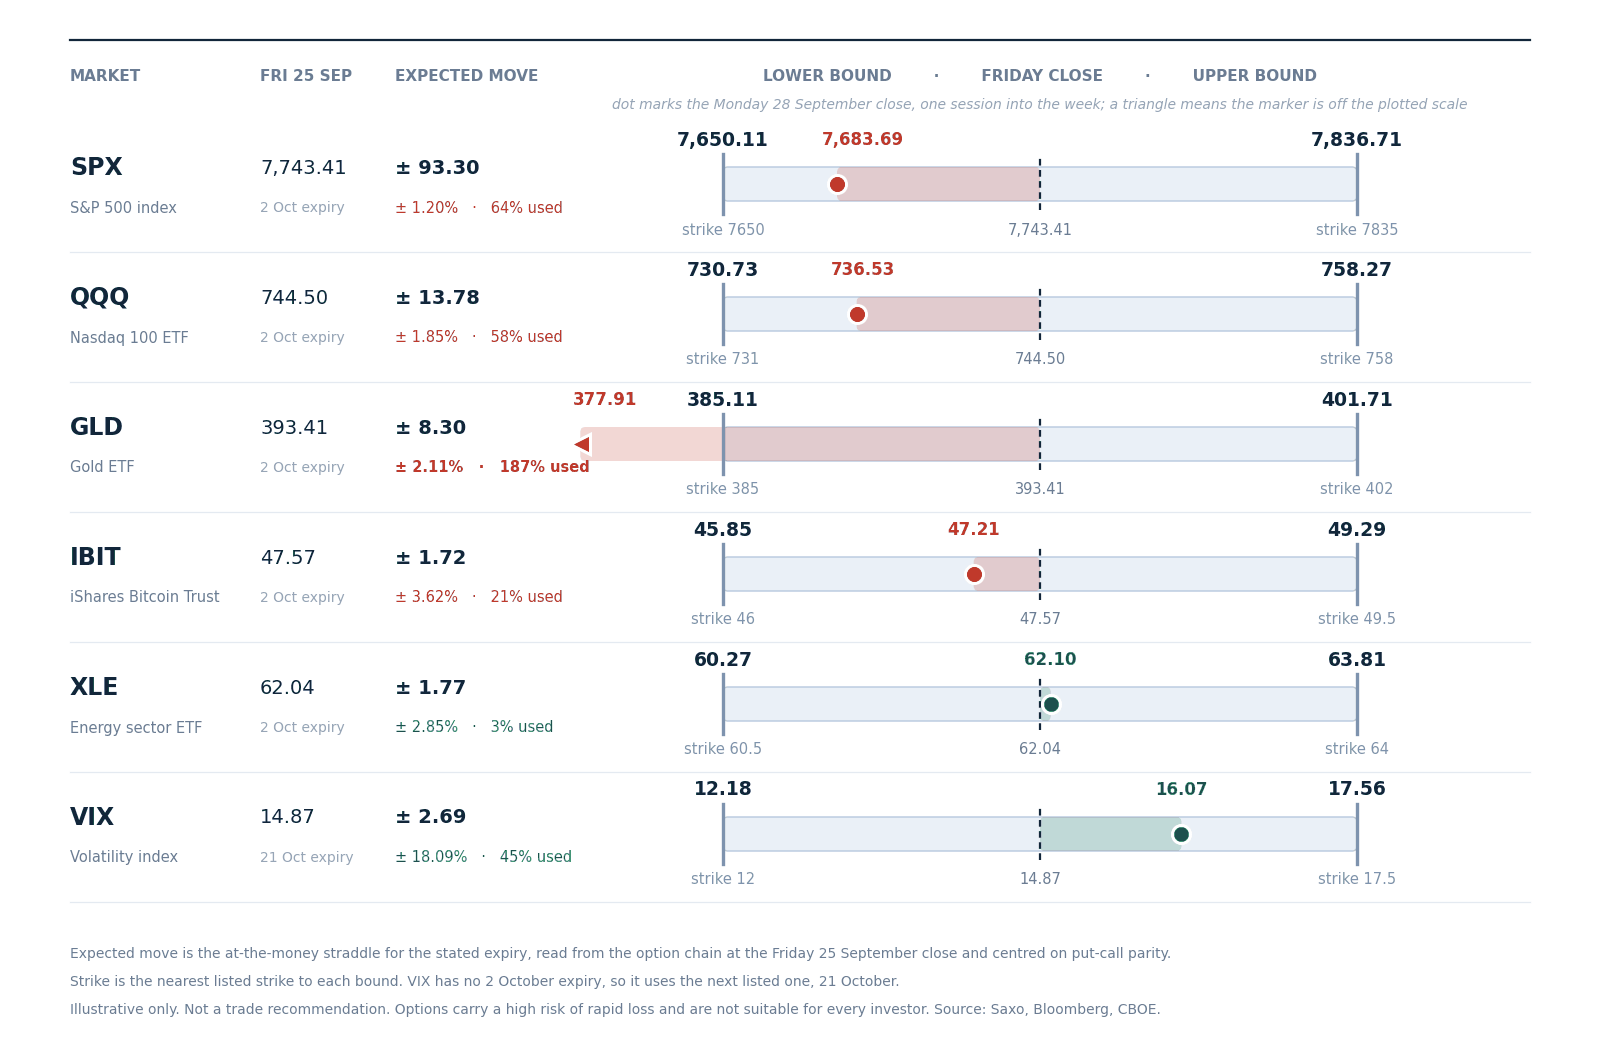 Expected move to Friday 2 October, drawn around the 25 September close with the nearest listed strike at each bound. Volatility uses the 21 October expiry, whose forward sits above spot. Read from the chain at Friday's close, not a forecast.
- One session into five, the gold fund has already spent the whole week. It closed at 377.91 against a lower bound of 385.11, using 187% of the whole week's priced range in a day. Nothing else came close: the S&P 500 has used 64%, the Nasdaq 100 fund 58%, the bitcoin fund 21% and energy 3%.
- The index band has been marked up since it was drawn. That expiry priced 93.30 points at Friday's close with five sessions to run and prices about 89 points now with four. Pure decay alone would have left roughly 86, so a little premium has been added rather than taken out. Options carry a high risk of rapid loss and are not suitable for every investor; see Saxo pricing for costs and charges.
The US cash session runs 15:30 CET to 22:00 CET. August JOLTS job openings and September consumer confidence both arrive at 16:00 CET, half an hour after the open and inside the session, so today's expiry prices them and the six hours that follow. Spain's flash CPI came at 09:00 CET and euro-zone confidence surveys at 11:00 CET. Carnival reports.
The heavier half of the week is still ahead. Wednesday brings the August core PCE deflator at 14:30 CET, an hour before the open, with Micron after the close. Thursday carries ISM manufacturing at 16:00 CET, and Friday the September employment report at 14:30 CET, alongside euro-zone flash inflation. Future outcomes are uncertain and may result in losses.
- Session implied move. SPXW options price about 40 points, 0.52%, to tonight's 22:00 CET close, against 43 a session ago: the day marked down as the week marked up. Quotes ahead of the US open are indicative.
- Event implied range. The 2 October expiry prices 89 points, 1.16%, covering core PCE, ISM and payrolls. It priced 93.30 at Friday's close with one more session left; decay alone would have left 86.
- Where volatility is being paid for. MOVE at 101.82 tops 59 of the previous 60 readings while the VIX sits at 29% of its own range. In our assessment the market is paying for rates risk, not equity risk, and the single-name ranks agree.
- Correlation and tails. COR3M rose 6.59% to 11.00, only 14 of the previous 60 higher, with SKEW at 146.25. In our view correlation rising alongside an elevated skew is the part of Monday that was not a rate move.
On Friday the front of the curve priced this data week as ordinary. Monday put the premium back into the nine-day window and took it out of today.
The wider gap is between assets, not tenors: rates volatility at the top of its two-month range, equity volatility in the bottom third of its own, into payrolls. Options carry a high risk of rapid loss.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it's crucial to make informed decisions.
| More from the author |
|---|